
Annapolis Mortgage Lender | Home Loans in MD
Whether you're buying your first home, refinancing, investing, or building a new home, Redwood Mortgage Services provides personalized mortgage guidance and a wide range of financing solutions tailored to your goals in Annapolis, Anne Arundel County, and throughout Maryland, Virginia, Washington, D.C., Delaware, North Carolina, and Florida.
From Conventional, FHA, VA and USDA loans to Jumbo, Construction, DSCR and Non-QM financing, we help borrowers understand their options and move forward with confidence
410-266-1621
Why Homebuyers Choose Redwood Mortgage Services
- ✓ Serving borrowers since 1999
- ✓ Local mortgage experts
- ✓ Purchase / Refinance / VA / Construction / Investment
- ✓ Fast communication
- ✓ Personalized guidance
- ✓ Competitive financing solutions
- ✓ Licensed in MD, VA, DC, DE, NC, FL
Choose the Mortgage That's Right for You
Find the right mortgage with competitive rates and expert guidance to help you buy your next home.
Lower your monthly payment, shorten your loan term, or access your home's equity with a refinance.
We'll guide you through every step and help you explore loan options designed for first-time buyers.
Eligible veterans, active-duty service members, and military families can take advantage of exclusive VA home loan benefits.
A construction loan provides financing in stages as the construction project progresses.
Jumbo loans allow qualified borrowers to purchase homes that exceed conforming loan limits without splitting financing into multiple loans.
What Our Customers Say About Us
 Reviews

2 weeks ago
 View on Google

3 months ago
View on Google

3 months ago
View on Google

4 months ago
View on Google

6 months ago
View on Google

7 months ago
View on Google

8 months ago
View on Google

8 months ago
View on Google

9 months ago
View on Google

9 months ago
View on Google

11 months ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google


1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

1 year ago
View on Google

2 years ago
View on Google

2 years ago
View on Google

2 years ago
View on Google

2 years ago
View on Google

2 years ago
View on Google
2 years ago
View on Google
2 years ago
View on Google
2 years ago
View on Google
2 years ago
View on Google
2 years ago
View on Google

3 years ago
View on Google

3 years ago
View on Google
3 years ago
View on Google
3 years ago
View on Google
3 years ago
View on Google

3 years ago
View on Google
3 years ago
View on Google
3 years ago
View on Google

3 years ago
View on Google
3 years ago
View on Google
3 years ago
View on Google
3 years ago
View on Google
3 years ago
View on Google

3 years ago
View on Google
3 years ago
View on Google

3 years ago
View on Google
4 years ago
View on Google
4 years ago
View on Google
5 years ago
View on Google
5 years ago
View on Google
5 years ago
View on Google
5 years ago
View on Google
5 years ago
View on Google
5 years ago
View on Google
5 years ago
View on Google
6 years ago
View on Google

6 years ago
View on Google
6 years ago
View on Google
6 years ago
View on Google
6 years ago
View on Google
6 years ago
View on Google

6 years ago
View on Google

6 years ago
View on Google
6 years ago
View on Google

6 years ago
View on Google
Mortgage Learning Center
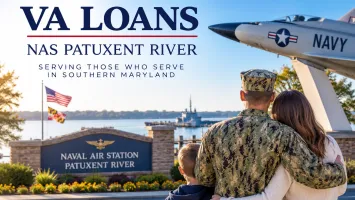
VA Loans Near NAS Patuxent River: A Homebuying Guide for Military Families in Southern Maryland
Sep 18, 2026
PCSing to NAS Patuxent River? Learn how VA loans work when buying a home in Lexington Park, California, Leonardtown and Southern Maryland.
VA Loans Near the U.S. Naval Academy: A Guide for Military Homebuyers in Annapolis
Sep 10, 2026
Learn how VA loans work for veterans, active-duty service members and military families buying a home in Annapolis, MD, including eligibility, occupancy, entitlement and VA appraisals.
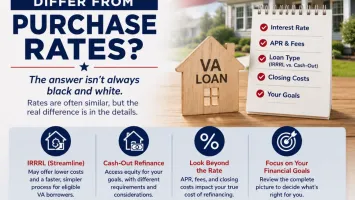
Do VA Refinance Rates Differ from Purchase Rates?
Jun 24, 2026
Do VA refinance rates differ from purchase rates? Learn how IRRRLs, cash-out refinancing, fees and loan structure can affect your overall costs.
Comparing Closing Costs Across the Country
Sep 30, 2026
Closing costs vary widely by state. Learn what drives mortgage closing costs, where buyers pay more, and how to budget ahead.
Should First-Time Buyers Consider a Lease Option?
Sep 23, 2026
Learn how a lease option works, key pros and risks, and when it may help first-time buyers move toward homeownership.
VA Loans Near NAS Patuxent River: A Homebuying Guide for Military Families in Southern Maryland
Sep 18, 2026
PCSing to NAS Patuxent River? Learn how VA loans work when buying a home in Lexington Park, California, Leonardtown and Southern Maryland.
Buying a home doesn't have to be confusing. Watch this short overview to see how the mortgage process works from application to closing
Ready to Take the Next Step?
Whether you're buying your first home, refinancing, building a home, or investing in real estate, we're here to help.
Main Phone: 410-266-1621
Stuart Direct: 410-266-1641
Frequently Asked Questions
Pre-qualification is generally an initial estimate of how much you may be able to borrow based on information you provide. A mortgage pre-approval typically involves a more detailed review of your income, assets, credit and other financial information. Requirements vary by loan program and lender, and a pre-approval is not a final loan approval.
Refinancing may make sense when it helps you achieve a specific financial goal, such as changing your loan term, moving from an adjustable-rate to a fixed-rate mortgage, accessing home equity, or obtaining different loan terms. When considering a refinance, it is important to compare the potential benefits with closing costs and how long you expect to keep the loan. A mortgage professional can help you evaluate the costs, available options and potential break-even period based on your individual circumstances.
A mortgage rate lock generally allows a borrower to secure an interest rate for a specified period while the loan is being processed, subject to the terms and conditions of the lock. Rate locks typically include the loan program, interest rate, any applicable points or pricing adjustments, and the length of the lock period. Lock periods and available terms can vary by lender and loan program.
A mortgage broker helps borrowers evaluate loan options from multiple lenders or wholesale lending sources, while a direct lender typically offers mortgage products available through its own lending channels. A mortgage broker can help compare available programs, explain qualification requirements and coordinate the loan process. The best option depends on the borrower’s financial situation, property and financing needs.
A conforming loan is a conventional mortgage that meets the eligibility requirements established by Fannie Mae or Freddie Mac, including applicable loan limits and underwriting guidelines. Conforming loan limits are established annually and may vary based on the property location and number of units.
A jumbo mortgage is a home loan with an amount that exceeds the applicable conforming loan limit for the property. Because jumbo loans are not eligible for purchase by Fannie Mae or Freddie Mac under conforming loan guidelines, they may have different credit, income, asset and down payment requirements. Loan limits vary by location and are updated periodically.
Mortgage points are fees calculated as a percentage of the loan amount. One point equals 1% of the loan amount. Depending on the loan and pricing structure, borrowers may have the option to pay discount points at closing in exchange for a lower interest rate. Whether paying points makes sense depends on the cost, potential interest savings and how long you expect to keep the loan.
Getting pre-approved before shopping for a home can help you establish a realistic price range and better understand your financing options. A pre-approval can also demonstrate to sellers that you have taken steps toward securing financing, which may strengthen an offer in a competitive market. A pre-approval is not a commitment to lend or a final loan approval.
Mortgage pre-approvals are commonly valid for a limited period, often around 60 to 90 days, although requirements vary by lender and loan program. If your pre-approval expires, updated financial information or a new credit review may be needed. Changes to your income, debts, assets, credit or employment can also affect your qualification.
A mortgage pre-approval typically requires a hard credit inquiry, which may have a small, temporary effect on your credit score. Multiple mortgage inquiries made within a short shopping window are generally treated as a single inquiry by many credit scoring models. The exact impact can vary depending on your credit profile and the scoring model used.
In many cases, yes. A pre-approval generally does not require you to obtain your mortgage from that lender. However, changing lenders after you are under contract may affect the loan timeline because the new lender will need to complete its own review and approval process. Before making a change, consider your financing terms and closing deadline.
Both professionals play important roles in the homebuying process. Many buyers benefit from speaking with a mortgage professional early to understand their financing options, estimated price range and potential qualification before beginning their home search. A Realtor can then help identify properties that fit the buyer’s needs and budget.
Redwood Mortgage Services offers a range of financing options for homebuyers, homeowners and real estate investors, including conventional, FHA, VA, USDA, jumbo, construction, DSCR, bank statement, non-QM, bridge and reverse mortgage loans. Available programs and qualification requirements vary.
Yes. Redwood Mortgage Services works with eligible veterans, active-duty service members and other qualified borrowers using VA home loan benefits. We help borrowers understand VA eligibility, financing options and the mortgage process.
Yes. Self-employed borrowers may qualify using traditional income documentation or, when appropriate, alternative programs such as bank statement loans. Available options depend on the borrower's financial profile, property and loan requirements.
Yes. Redwood Mortgage Services offers construction financing for qualified borrowers building a home in Maryland. Construction financing may involve additional documentation such as builder information, plans, specifications, budgets and project timelines.
Redwood Mortgage Services is located at 2077 Somerville Rd., Suite 220, Annapolis, MD 21401. We help homebuyers, homeowners and real estate investors with mortgage financing in the states where we are appropriately licensed.