How to Read a Mortgage Loan Estimate: A Maryland Homebuyer's Guide
Published on Oct 09, 2026 | Mortgages Mortgage Advice #RedwoodMortgageServices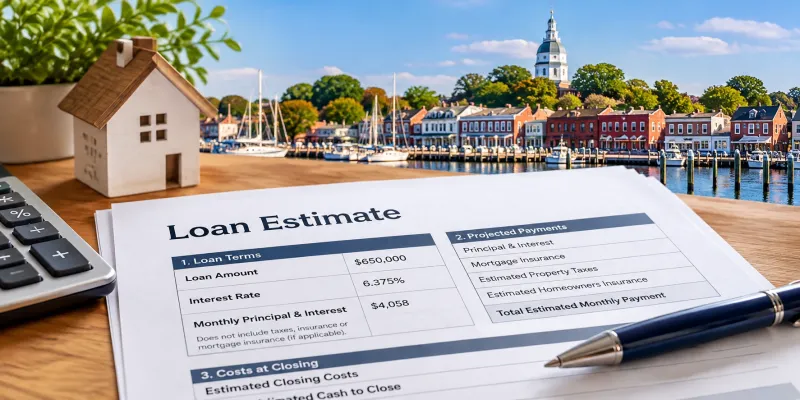
Quick Answer: A Loan Estimate is a three-page mortgage disclosure that helps homebuyers understand proposed loan terms, estimated monthly payments, closing costs, and cash needed at closing. Maryland borrowers can use it to compare mortgage offers, identify fees that may change, and ask informed questions before deciding which financing option best fits their needs.
Buying a home in Annapolis, Anne Arundel County, or elsewhere in Maryland involves more than choosing a property and finding an affordable monthly payment. Understanding the financing details is just as important.
One of the most useful documents you'll receive during the mortgage process is the Loan Estimate (LE). It gives you a standardized breakdown of important loan terms and estimated costs so you can review your options before moving forward.
At Redwood Mortgage Services, we believe borrowers should understand the numbers behind their mortgage—not just the interest rate.
What Is a Mortgage Loan Estimate?
A Loan Estimate is a standardized, three-page disclosure used for most closed-end consumer mortgages. It provides information about a proposed mortgage, including the loan amount, interest rate, estimated monthly payment, closing costs, and estimated cash needed at closing.
For mortgages subject to the federal Loan Estimate requirements, lenders generally must provide the disclosure within three business days after receiving the six pieces of information that constitute an application:
Your name
Your income
Your Social Security number, to obtain a credit report
The property address
An estimate of the property's value
The mortgage loan amount sought
You do not need to have selected a lender or completed every underwriting requirement to receive a Loan Estimate.
A Loan Estimate is not final loan approval, and its figures are not necessarily the final amounts you'll pay. However, it gives you an important starting point for evaluating mortgage financing.
Page 1: Understanding Your Mortgage Terms and Monthly Payment
The first page summarizes the most important features of your proposed loan.
Loan Terms
Review the following information:
Loan Amount: The amount you propose to borrow.
Interest Rate: The rate used to calculate interest on your loan. Check whether the rate can change after closing.
Monthly Principal and Interest: The payment toward your loan balance and interest, excluding items such as property taxes and homeowners insurance.
Also review the answers to these questions:
- Can the loan amount increase after closing?
- Can the interest rate increase after closing?
- Can the monthly principal and interest payment increase?
- Does the loan have a prepayment penalty?
- Does the loan include a balloon payment?
These details help you understand potential future payment changes—not just the initial payment.
Projected Payments
This section estimates your monthly housing payment, which may include:
- Principal and interest
- Mortgage insurance, when applicable
- Estimated property taxes
- Estimated homeowners insurance and certain other assessments
For Maryland homebuyers, property taxes and insurance can meaningfully affect affordability. A mortgage payment that initially appears manageable may look different once these costs are included.
Important: The projected payment is an estimate. Property taxes, insurance premiums, and other applicable expenses may change.
Costs at Closing
Near the bottom of Page 1, you'll find two important figures:
Estimated Closing Costs: The estimated fees and expenses associated with the transaction, including applicable loan costs and other closing-related items.
Estimated Cash to Close: The estimated amount you'll need to bring to closing after accounting for items such as your down payment, deposits, credits, and other adjustments.
These are not the same number.
A borrower may have a manageable monthly payment but still need to plan carefully for the funds required at closing.
Page 2: Understanding Closing Costs and Fees
Page 2 provides a more detailed breakdown of estimated closing costs.
Section A: Origination Charges
These are charges associated with making the mortgage loan. Depending on the loan, they may include lender origination fees, underwriting charges, and discount points.
Discount points are upfront charges that may be paid to obtain a different interest rate. Whether paying points makes financial sense depends on the cost, expected savings, and how long you anticipate keeping the loan.
Section B: Services You Cannot Shop For
This section includes certain services required by the lender for which you cannot select a different provider.
Examples may include an appraisal or credit report fee, depending on the transaction.
Section C: Services You Can Shop For
These are services for which the lender permits you to select a provider, subject to applicable requirements.
Depending on the transaction, examples may include certain title-related or settlement services.
Reviewing this section can help you understand where provider selection may affect your costs.
Sections E–H: Other Closing Costs
These sections may include:
- Recording fees and applicable transfer taxes
- Prepaid interest and insurance
- Initial escrow payments
- Certain other settlement charges
- Lender credits, if applicable
In Maryland, transfer and recordation taxes can be important parts of a purchase transaction. The amount and allocation may depend on the property location, transaction terms, and applicable exemptions or requirements.
Ask your lender and settlement professional how these charges apply to your specific purchase.
Calculating Cash to Close
Page 2 also shows how the estimated cash-to-close amount is calculated.
Depending on the transaction, this calculation can reflect your down payment, closing costs, deposits, seller credits, lender credits, and other adjustments.
A useful question to ask: “How much money should I plan to have available before closing, and which parts of this estimate could still change?”
Page 3: Comparing Mortgage Offers
Page 3 includes information that can help you evaluate the loan beyond its monthly payment.
Annual Percentage Rate (APR)
The APR represents the cost of credit expressed as a yearly rate. It incorporates the interest rate and certain finance charges, such as applicable lender fees and discount points.
APR is not the same as the mortgage interest rate.
It also does not generally include ordinary property taxes or amounts deposited into an escrow account for taxes and insurance.
When comparing loans, APR can be helpful, especially when reviewing offers with similar loan structures. However, APR alone does not tell you which loan is best for your circumstances.
Total Interest Percentage (TIP)
The Total Interest Percentage estimates the total interest you would pay over the life of the loan as a percentage of the loan amount, assuming payments are made as scheduled.
This can help illustrate the long-term cost of borrowing.
Other Considerations
Page 3 also provides information about matters such as:
- Whether the lender intends to service the loan or transfer servicing
- Whether the loan can be assumed by another borrower under certain conditions
- Late-payment terms
- Appraisal-related information
- Refinancing considerations
Review these disclosures and ask questions about anything you don't understand.
How Do You Compare Loan Estimates From Different Mortgage Lenders?
One of the biggest advantages of the Loan Estimate is that lenders use a standardized format.
That makes it easier to compare offers—but only if you're comparing similar terms.
Before comparing two Loan Estimates, confirm that the offers use the same or comparable:
- Loan amount and repayment term
- Loan type, such as conventional, FHA, or VA
- Fixed or adjustable interest-rate structure
- Interest-rate lock status and lock period
- Discount-point assumptions
- Estimated closing date
Then review the interest rate, monthly payment, APR, origination charges, lender credits, estimated cash to close, and any significant differences in third-party fees.
A lower interest rate does not automatically mean a lower overall cost.
For example, one offer may have a lower rate but require more upfront discount points. Another may have a slightly higher rate with lower upfront lender charges.
The right comparison depends on your budget, how long you expect to keep the mortgage, and your broader financial goals.
Can Your Loan Estimate Change Before Closing?
Yes, certain estimated costs and loan terms can change, but federal disclosure rules limit when lenders may use a revised Loan Estimate to reset applicable closing-cost tolerances.
Depending on the circumstances, a permitted revision may involve a qualifying change in circumstances, a borrower-requested change, certain rate-lock developments, or another event recognized by the applicable rules.
Not every change automatically permits a lender to increase previously disclosed charges.
Some charges generally have zero tolerance for increases, some are subject to an aggregate 10% tolerance, and others may change without a specified tolerance limit, subject to applicable conditions.
If you receive a revised Loan Estimate, compare it with the earlier version and ask your lender to explain the differences.
Loan Estimate vs. Closing Disclosure: What's the Difference?
The Loan Estimate and Closing Disclosure serve different purposes.
The Loan Estimate is provided earlier in the mortgage process and shows proposed loan terms and estimated costs.
The Closing Disclosure (CD) provides the final loan terms and closing-cost details for the transaction.
For most mortgages subject to the federal Closing Disclosure requirements, the borrower must receive the Closing Disclosure at least three business days before consummation.
Use that time to compare the Closing Disclosure with your most recent Loan Estimate.
If a charge, interest rate, payment, or other important detail differs from what you expected, ask for an explanation before proceeding.
Why Understanding Your Loan Estimate Matters in Maryland
Whether you're purchasing a home in Annapolis, Severna Park, Arnold, Edgewater, Crofton, or another Maryland community, the financing decision involves more than the advertised mortgage rate.
Property taxes, insurance, closing expenses, loan structure, and the funds required at settlement can all influence your decision.
Redwood Mortgage Services helps eligible borrowers explore mortgage financing options, including conventional, FHA, VA, jumbo, and other available programs.
Our approach is to review the financing details, answer questions, and help borrowers understand their options before making a commitment.
Frequently Asked Questions About Mortgage Loan Estimates
Is a Loan Estimate the same as mortgage approval?
No. A Loan Estimate provides proposed terms and estimated costs. It does not mean your loan has received final underwriting approval.
Does receiving a Loan Estimate lock my mortgage interest rate?
Not necessarily. The Loan Estimate identifies whether your rate is locked and, if so, the applicable lock expiration information. Ask your lender to confirm the status of your rate.
Do I have to pay for a Loan Estimate?
For mortgages subject to the applicable federal rules, a lender generally cannot charge fees before you indicate your intent to proceed, except for a bona fide and reasonable credit-report fee.
Can I receive Loan Estimates from multiple lenders?
Yes. Comparing Loan Estimates from different lenders can help you evaluate financing options. Try to compare offers with equivalent terms and similar rate-lock assumptions.
Why is my cash to close higher than my closing costs?
Cash to close can include your down payment and other adjustments in addition to closing costs. Deposits, seller credits, and lender credits may reduce the amount you need to bring.
What should I do if I don't understand a fee?
Ask your lender to explain what the fee covers, who receives it, whether it can change, and whether you have the option to select a different service provider.
Can closing costs change after I receive my Loan Estimate?
Yes, depending on the charge and circumstances. Federal rules restrict certain increases, while other amounts may vary. Your lender should explain material differences between disclosures.
Related Reading
How Much Cash Do You Really Need to Buy a Home?
Explore down payments, closing costs, and other expenses that influence the funds needed for a home purchase.
How Much House Can You Afford in Anne Arundel County in 2026?
Understand how your monthly housing payment fits into an overall affordability calculation.
The Mortgage Mistake Costing Buyers Negotiating Power
Learn why preparing your financing early can matter when you're ready to make an offer.
Have Questions About Your Mortgage Loan Estimate?
A Loan Estimate should help you understand your financing—not leave you with more questions.
If you're buying or refinancing a home in Maryland, Redwood Mortgage Services can help you review your proposed mortgage terms, understand estimated costs, and explore available financing options.
Stuart Kiehne | NMLS #92008
Redwood Mortgage Services
Phone: 410-266-1621
Website: www.Redwood-Mortgage.com
Schedule a Consultation:
https://calendly.com/stuart-70/introduction-and-conversation
All loans subject to approval. Equal Housing Lender.