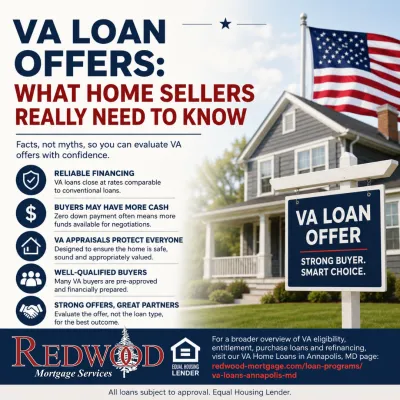
When a home seller receives an offer from a buyer using VA financing, the words “VA loan” can sometimes create unnecessary concern.
Some sellers worry that VA financing means a difficult appraisal, excessive repair requirements, a buyer with weak finances or a greater chance that the transaction won't close.
Many of these concerns come from misunderstandings about how VA-backed home loans actually work.
A VA loan is a mortgage made by a private lender and backed in part by the U.S. Department of Veterans Affairs. Eligible veterans, active-duty service members and certain surviving spouses may use the program to purchase a home, subject to VA and lender requirements.
If you're selling a home in Annapolis, Anne Arundel County or elsewhere in Maryland, understanding the basics of VA financing can help you evaluate a VA-financed offer based on the actual terms rather than the loan type alone.
Does Zero Down Mean a VA Buyer Is Financially Weak?
No.
One of the primary benefits of VA financing is that eligible borrowers may be able to purchase a home without a required down payment when applicable requirements are met. VA reports that nearly 90% of VA-backed home loans are made without a down payment.
That doesn't mean the lender ignores the borrower's finances.
VA-backed borrowers must meet applicable VA and lender requirements involving credit, income and other qualification factors. The lender—not VA—ultimately determines whether the borrower qualifies for the mortgage.
A seller therefore shouldn't interpret a zero-down VA offer as evidence that the buyer is financially unqualified.
The strength of an offer should be evaluated based on the buyer's financing approval, contract terms and overall transaction—not simply the size of the down payment.
Are VA Loans Harder to Close?
A VA loan does include requirements that differ from conventional financing, but that doesn't mean every VA transaction is inherently more difficult.
As with any financed purchase, a successful closing depends on factors such as the borrower's qualification, the property's appraised value and condition, title issues, documentation and the lender's processing of the loan.
One of the best things a seller and listing agent can do when evaluating a VA offer is look beyond the loan label.
Questions worth considering include:
- Has the buyer been pre-approved?
- Has the lender reviewed the buyer's income, assets and credit?
- Is the lender familiar with VA financing?
- Are the contract terms clear?
- Is the proposed closing timeline reasonable?
- Is the lender communicating effectively with the buyer's real estate agent?
Those details can tell a seller considerably more about the strength of an offer than the fact that the buyer is using a VA loan.
What Is Different About a VA Appraisal?
A VA-backed purchase generally requires an appraisal completed by a VA-approved appraiser.
Like other mortgage appraisals, the VA appraisal provides an opinion of the property's value.
However, the VA appraisal also considers whether the property meets VA's Minimum Property Requirements, commonly called MPRs.
These requirements are intended to address basic property conditions associated with safe, sound and sanitary housing.
Importantly, a VA appraisal isn't the same thing as a home inspection. VA itself recommends that buyers consider obtaining a separate professional home inspection.
Did VA Change Its Property Requirements in 2026?
Yes.
In June 2026, VA announced updates to its Minimum Property Requirements intended to reduce appraisal delays, eliminate certain outdated requirements and help veteran homebuyers compete more effectively in today's housing market.
Among the changes were revisions involving radon requirements and standards affecting properties built before and after 1978. The revised requirements are now reflected in the VA Lenders Handbook.
This is important for sellers and real estate agents because some perceptions about VA property requirements may be based on older rules.
That doesn't mean property condition no longer matters. A home still must meet applicable VA requirements.
But sellers shouldn't assume that a VA appraisal automatically means an unreasonable list of repairs.
What Happens If a VA Appraisal Identifies a Property Issue?
If an appraisal identifies a condition that must be addressed for the property to satisfy applicable VA requirements, the issue will generally need to be resolved before the loan can proceed as a VA-guaranteed purchase.
That doesn't necessarily mean the transaction is over.
The buyer, seller, real estate agents and lender can evaluate the particular issue and determine what options may be available.
This is another reason experienced communication among the parties can make an important difference in a VA transaction.
What Happens If the VA Appraisal Comes in Below the Purchase Price?
A low appraisal doesn't automatically end a VA transaction.
VA identifies several possible options when the appraised value is below the contract price. Depending on the circumstances, the parties may be able to:
- Request a Reconsideration of Value using appropriate market information
- Renegotiate the purchase price
- Have the buyer pay some or all of the difference between the appraised value and contract price
- Use the VA appraisal contingency when applicable
VA specifically provides a Reconsideration of Value process when there is information that may support a different valuation.
What Is the VA Escape Clause?
VA purchase contracts generally include what's commonly called the VA escape clause or VA option clause.
The clause protects the VA buyer from being obligated to complete the purchase solely because the contract price exceeds the property's VA-established reasonable value.
Importantly, this doesn't prohibit a veteran from proceeding with the purchase.
VA states that if the property appraises below the purchase price, the buyer may have options that include renegotiating the price, requesting a Reconsideration of Value or paying the difference in cash.
For sellers, understanding this distinction is important. A low appraisal creates an issue to resolve, but it doesn't automatically terminate the transaction.
Can a Seller Pay a VA Buyer's Closing Costs?
Yes.
VA permits sellers or builders to provide credits toward some or all of a buyer's allowable closing costs.
There is also an important distinction between closing costs and seller concessions under VA rules.
VA's 4% limitation applies to seller concessions—not simply to every closing cost a seller may agree to pay. VA identifies examples of concessions such as paying the VA funding fee, certain prepaid taxes and insurance, debt payoff and certain interest-rate buydowns.
That flexibility can sometimes help buyers and sellers structure a transaction that works for both parties.
Does the Seller Have to Pay All of the VA Buyer's Costs?
No.
The fact that a buyer is using VA financing doesn't mean the seller automatically has to pay all of the buyer's closing costs.
Who pays various allowable costs can depend on VA requirements, the purchase contract, local practices and negotiations between the parties.
Sellers should evaluate the actual requested credits or concessions in the offer rather than assuming that accepting VA financing automatically creates a large seller expense.
Should Sellers Be Concerned About VA Buyers?
A seller should evaluate any financed offer carefully.
But the fact that the buyer is using an earned VA home loan benefit shouldn't, by itself, be viewed as a weakness.
Instead, sellers and their agents should consider the complete offer:
- Purchase price
- Buyer's pre-approval
- Requested seller credits or concessions
- Earnest money
- Appraisal and other contingencies
- Proposed closing date
- Property condition
- Lender communication
- Other terms important to the seller
A well-qualified VA buyer with a strong pre-approval and well-structured offer may be an excellent candidate to purchase a home.
For Real Estate Agents: Help Sellers Evaluate the Offer, Not the Loan Label
Listing agents can play an important role in helping sellers understand VA financing.
When presenting a VA offer, it can be helpful to distinguish actual contract terms from assumptions about the program.
If a seller's concern involves the appraisal, property condition, closing costs or financing approval, those specific concerns can often be evaluated directly.
This can help sellers make an informed decision while ensuring veteran and military buyers receive fair consideration based on the strength of their offer.
Explore VA Home Loan Options
VA financing provides eligible veterans, active-duty service members and certain surviving spouses with an important homeownership benefit.
Redwood Mortgage Services works with veterans, military families and real estate professionals to help structure VA-financed home purchases and provide clear communication throughout the mortgage process.
For a broader overview of VA eligibility, entitlement, purchase loans and refinancing, visit our VA Home Loans in Annapolis, MD page:
VA Home Loans in Annapolis, MD
All loans subject to approval. Equal Housing Lender.
Frequently Asked Questions
Are VA loans harder for sellers to accept?
Not necessarily. VA loans have requirements that differ from conventional financing, including a VA appraisal and certain property requirements, but the financing type alone doesn't determine the strength of an offer. Sellers should consider the buyer's pre-approval, contract terms, requested concessions, proposed closing date and other details of the transaction.
Does a VA buyer have to make a down payment?
Not necessarily. Eligible VA borrowers may be able to purchase a home without a required down payment when applicable requirements are met. A zero-down VA offer shouldn't, by itself, be interpreted as evidence that the buyer is financially unqualified.
Does a VA appraisal require the seller to make repairs?
Not automatically. If the VA appraisal identifies a property condition that must be addressed to satisfy applicable VA requirements, that particular issue may need to be resolved before the purchase can proceed with VA financing. A VA appraisal doesn't automatically mean a seller will receive an extensive repair list.
What happens if a VA appraisal is lower than the purchase price?
A low VA appraisal doesn't automatically end the transaction. Depending on the circumstances, options may include requesting a Reconsideration of Value, renegotiating the purchase price or having the buyer pay some or all of the difference between the appraised value and contract price.
Can a seller pay closing costs for a VA buyer?
Yes. Sellers may pay certain allowable closing costs for a VA buyer. VA also permits certain seller concessions, although specific rules apply to how those concessions are structured.
Is there a 4% limit on everything a seller can pay for a VA buyer?
No. VA's 4% limitation applies to certain seller concessions, not simply to every allowable closing cost a seller may pay. Closing costs and seller concessions are treated differently under VA rules.
Should a seller reject an offer because the buyer is using a VA loan?
The financing type alone doesn't determine the strength of an offer. Sellers and their real estate agents can evaluate the complete terms of a VA-financed offer—including price, pre-approval, requested credits or concessions, contingencies, closing date and other factors—just as they would evaluate other financed offers.
Related Reading
VA Loan Closing Costs and Fees: What Veterans Should Know
Learn how VA closing costs, the funding fee, seller-paid costs and seller concessions work—including the important distinction involving VA's 4% seller-concession limit.
5 Common VA Loan Myths Veterans in Anne Arundel County Should Know
Separate fact from fiction about VA financing, including misconceptions involving zero-down financing, credit, sellers, entitlement and the VA appraisal process.
How to Qualify for a VA Loan in 2026: Eligibility, Requirements & Pre-Approval
Learn how VA eligibility, entitlement, income, credit and pre-approval work when an eligible veteran or service member prepares to purchase a home.
Written by Charles Stuart Kiehne, President of Redwood Mortgage Services.
Stuart has helped homebuyers and homeowners with mortgage financing solutions since 1999 and is licensed in Maryland, Virginia, Washington DC, Delaware, North Carolina, and Florida.
NMLS #92008