For many veterans and active-duty service members, VA loans offer one of the most accessible and cost-effective paths to homeownership. But when it comes time to refinance, an important question often comes up: do VA refinance rates differ from purchase rates?
At first glance, the answer seems simple. However, once you look beyond the surface, the full picture becomes more nuanced. Understanding how interest rates, fees, and loan structures differ between purchase and refinance loans can help you make a more informed financial decision.
The Short Answer
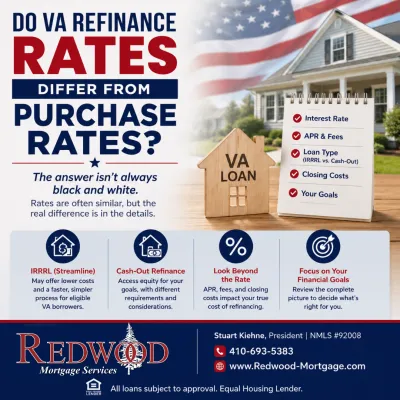
Yes, VA refinance rates and VA purchase rates may differ, but there isn't a single rule that always applies.
Mortgage rates are influenced by many factors, including market conditions, the type of refinance, loan term, credit profile, equity, and lender pricing.
The best way to compare your options is to review current refinance scenarios based on your individual financial goals rather than assuming refinance rates will always be higher or lower than purchase rates.
Interest Rates: More Similar Than Different
In most cases, VA refinance rates and VA purchase rates are very close to one another. Because both loan types are backed by the same government guarantee, lenders typically price them similarly in terms of base interest rates.
This means that if current VA purchase rates are in a certain range, refinance rates will often fall within that same range, assuming similar borrower qualifications such as credit score, income, and loan terms.
However, focusing only on the interest rate can be misleading. While the rate itself may be similar, the overall cost of the loan can vary depending on the type of refinance and the associated fees.
Why APR Tells a Different Story
To understand the real cost of a loan, it is important to look at the annual percentage rate (APR), not just the interest rate. APR includes both the interest rate and the additional costs associated with the loan, such as lender fees, closing costs, and funding fees.
This is where refinance loans—particularly certain VA refinance options—can differ significantly from purchase loans.
Even if two loans have the same interest rate, the one with lower fees will have a lower APR. Over time, this can translate into meaningful savings.
Factors That May Affect VA Refinance Rates
While interest rates are important, they are only one part of the refinancing decision. The type of VA refinance loan you choose may also affect your overall borrowing costs, closing expenses, and long-term financial goals. Understanding the differences between available refinance options can help you determine which approach best fits your situation.
Several factors can influence the interest rate offered on a VA refinance loan, including:
Current mortgage market conditions
Credit profile
Loan term (15-year vs. 30-year)
Loan amount
Available home equity
Occupancy status
Type of refinance (VA IRRRL or VA Cash-Out Refinance)
Because every borrower's situation is unique, two veterans refinancing on the same day may receive different loan pricing.
The VA IRRRL: Refinancing an Existing VA Loan
The VA Interest Rate Reduction Refinance Loan (IRRRL), sometimes called a VA Streamline Refinance, is available to eligible borrowers who already have a VA-backed home loan.
An IRRRL may be used to replace the existing VA loan with a new VA-backed loan that reduces the monthly payment through a lower interest rate or makes the payment more stable, such as refinancing from an adjustable-rate mortgage to a fixed-rate mortgage.
IRRRL requirements differ from those of a VA purchase loan or VA Cash-Out Refinance. For example, VA does not require an appraisal or credit underwriting package for an IRRRL, although individual lenders may have their own requirements.
Closing costs may also be included in the new loan in certain circumstances. The VA funding fee for an IRRRL is currently 0.5%, unless the borrower qualifies for an exemption.
Because rates, fees and lender requirements can vary, borrowers should evaluate the complete refinance proposal rather than assuming an IRRRL will automatically provide the lowest-cost option.
VA Cash-Out Refinancing: A Different Scenario
A VA Cash-Out Refinance is different from an IRRRL. It may allow an eligible borrower to refinance an existing VA or non-VA mortgage into a new VA-backed loan and, depending on available equity and lender requirements, potentially receive cash from the home's equity.
Unlike an IRRRL, a VA Cash-Out Refinance generally involves a new appraisal and a more complete review of the borrower's financial qualifications.
The interest rate and costs available on a cash-out refinance depend on the borrower, property, loan structure, market conditions and lender pricing. Rather than assuming a cash-out refinance will carry a particular rate, compare the complete loan terms and costs.
Comparing the Full Financial Picture
When deciding whether to refinance, it is important to look beyond the headline rate and evaluate the full financial impact. This includes total closing costs, monthly payment changes, and how long you plan to stay in the home.
For example, if refinancing saves you $150 per month but costs $3,000 in closing expenses, it would take 20 months to break even. If you plan to stay in the home longer than that, the refinance may provide long-term savings.
VA refinancing also includes program-specific requirements designed to help ensure certain refinances provide a financial benefit to the Veteran. Depending on the type of VA refinance, requirements involving payment reduction, interest rate, loan term, seasoning or recoupment of certain closing costs may apply.
VA Refinancing in Annapolis and Anne Arundel County
Many veterans and military families throughout Annapolis, Arnold, Severna Park, Edgewater, Crofton, Davidsonville, Pasadena, Odenton, and the surrounding Anne Arundel County area periodically review their mortgage to determine whether refinancing may support their financial goals.
Whether you're responding to changing market conditions, planning for retirement, or simply reviewing your current mortgage, refinancing is a decision that deserves careful consideration.
When Does a VA Refinance Make Sense?
Every homeowner's financial goals are different. While refinancing isn't the right choice for everyone, there are several situations where eligible veterans may want to explore whether a VA refinance could support their long-term objectives.
Lowering Your Monthly Mortgage Payment
Some homeowners refinance to potentially reduce their monthly mortgage payment. This may be possible if market conditions, loan terms, and individual qualifications align favorably.
Lower monthly payments can improve monthly cash flow, although extending the repayment term could increase the total interest paid over the life of the loan. Reviewing the overall financial impact—not just the monthly payment—is important.
Paying Off Your Home Sooner
Not every refinance is about lowering payments. Some veterans choose to refinance into a shorter loan term, such as moving from a 30-year mortgage to a 15-year mortgage.
While monthly payments may be higher, a shorter loan term can help build equity more quickly and may reduce the total interest paid over the life of the loan.
Accessing Home Equity Through a VA Cash-Out Refinance
As home values change over time, many homeowners build equity in their property.
A VA Cash-Out Refinance may allow eligible borrowers to access a portion of that equity for purposes such as:
Home improvements or renovations
Major planned expenses
Other financial goals
Replacing an existing mortgage with a new VA loan
The amount available depends on lender guidelines, property value, existing loan balance, and borrower qualifications.
Refinancing a Non-VA Loan Into a VA Loan
Some eligible veterans originally purchased their home using a conventional, FHA, or other mortgage program. Understanding your VA loan benefit and remaining entitlement is often an important first step before exploring refinance options.
Depending on eligibility and lender guidelines, it may be possible to refinance that existing loan into a VA loan. Reviewing your eligibility and discussing your situation with an experienced VA mortgage professional can help determine whether refinancing into a VA loan may be an option. Some homeowners explore this option to take advantage of VA loan features, such as the absence of monthly mortgage insurance on many VA loans.
Using Home Equity Strategically
For many homeowners, their home represents one of their largest financial assets.
A refinance may provide access to accumulated equity, but it is important to carefully evaluate how those funds will be used and how refinancing may affect long-term financial goals. Every situation is different, and understanding both the benefits and trade-offs can help homeowners make informed decisions.
Consolidating Higher-Interest Debt
Some homeowners consider using a VA Cash-Out Refinance to pay off higher-interest debt.
While this strategy may simplify monthly finances for some borrowers, it also converts unsecured debt into debt secured by the home. Because this decision can have long-term financial implications, it is important to carefully evaluate the overall costs, repayment timeline, and personal financial goals before proceeding.
Questions to Ask Before Refinancing
Before moving forward with a VA refinance, consider asking:
How long do I plan to stay in my home?
Will refinancing reduce my overall borrowing costs?
What are my estimated closing costs?
How long will it take to recover those costs through monthly savings?
Am I refinancing to lower my payment, shorten my loan term, or access equity?
Answering these questions can help determine whether refinancing aligns with your long-term financial goals.
There isn't a one-size-fits-all answer. A refinance that makes sense for one homeowner may not be the right choice for another. Reviewing these questions before applying can help ensure your refinancing decision supports your long-term financial objectives.
Will Refinancing Reset My Loan Term?
In many cases, refinancing replaces your existing mortgage with a new loan, which typically starts a new repayment schedule.
Depending on your goals, you may choose a shorter or longer loan term. While extending the term could reduce your monthly payment, it may also increase the total interest paid over the life of the loan. Reviewing your repayment options can help ensure the refinance aligns with your financial objectives.
Every Veteran's Situation Is Different
Refinancing is not simply about obtaining a different interest rate. It is about determining whether a new mortgage aligns with your current financial goals.
Whether you're looking to lower your monthly payment, shorten your loan term, access home equity, or simply understand your available options, reviewing your situation with an experienced VA mortgage professional can help you make an informed decision based on your individual circumstances.
Explore VA Home Loan Options in Annapolis, MD
Learn more about VA purchase and refinance options for eligible Veterans and military families in Annapolis, Anne Arundel County and throughout Maryland.
Related Reading
Continue Learning About VA Loans
How to Get a Better VA Loan Rate: What Veterans Should Know
Learn what can influence VA mortgage pricing and why comparing the complete loan—not just the advertised interest rate—is important.
How to Qualify for a VA Loan in 2026: Eligibility, Requirements & Pre-Approval
Learn how VA eligibility, Certificates of Eligibility, credit, income, entitlement and pre-approval work when preparing for VA financing.
VA Loan Closing Costs and Fees: What Veterans Should Know
Understand the VA funding fee, closing costs and other expenses that can affect the overall cost of VA financing.
The VA Loan Benefit Most Veterans Don't Know About
Learn how VA entitlement works and why eligible veterans may be able to use their VA home loan benefit more than once.
Top 10 Tips for Choosing a VA Lender in Annapolis, MD
Learn what Veterans and military homebuyers should consider when comparing VA lenders, including experience, fees, communication and local market knowledge.
Frequently Asked Questions
Do VA refinance rates usually differ from purchase rates?
In many cases, they are very similar, although the overall cost of the loan may differ because of closing costs, loan structure, and lender pricing.
What is a VA IRRRL?
A VA Interest Rate Reduction Refinance Loan (IRRRL) is a streamlined refinance program available to eligible homeowners who already have a VA loan.
Can I refinance a conventional loan into a VA loan?
Depending on eligibility and lender guidelines, some veterans may be able to refinance an existing conventional or FHA loan into a VA loan.
Will refinancing reset my mortgage?
In many cases, refinancing replaces your current mortgage with a new loan and a new repayment schedule. Borrowers can often choose a loan term that best fits their financial goals.
Can I access equity with a VA refinance?
Eligible homeowners may be able to use a VA Cash-Out Refinance to access a portion of their available home equity, subject to lender guidelines and qualifications.
Should I refinance just because interest rates have changed?
Not necessarily. It's important to consider the complete financial picture, including closing costs, loan term, monthly payment, and how long you expect to remain in the home.
Final Thoughts
VA refinance rates and purchase rates are often similar on the surface, but the true cost of each loan depends on more than just the interest rate. Factors such as fees, loan type, and overall structure can significantly impact what you pay over time.
By evaluating the complete financial picture—not just the rate—you can make a decision that supports both your immediate needs and long-term financial stability.
Every veteran's financial goals are different, which is why comparing refinance options should involve more than simply looking at today's interest rates. A personalized mortgage review can help you evaluate potential savings, loan costs, and the refinance strategies that best align with your long-term plans.
If you're considering a VA refinance, we'd be happy to review your current mortgage, discuss your financial goals, and help you compare the available options. Sometimes a short conversation is all it takes to determine whether refinancing makes sense for your situation.
Call 410-266-1641
Written by Charles Stuart Kiehne, President of Redwood Mortgage Services.
Stuart has helped homebuyers and homeowners with mortgage financing solutions since 1999 and is licensed in Maryland, Virginia, Washington DC, Delaware, North Carolina, and Florida.
NMLS #92008
All loans subject to approval. Equal Housing Lender.